Pasadena Title Insurance Guide: How to Shield Your Home Ownership
Khushboo Siddhiwala
Oct 13, 2026 · 7 min read
Story
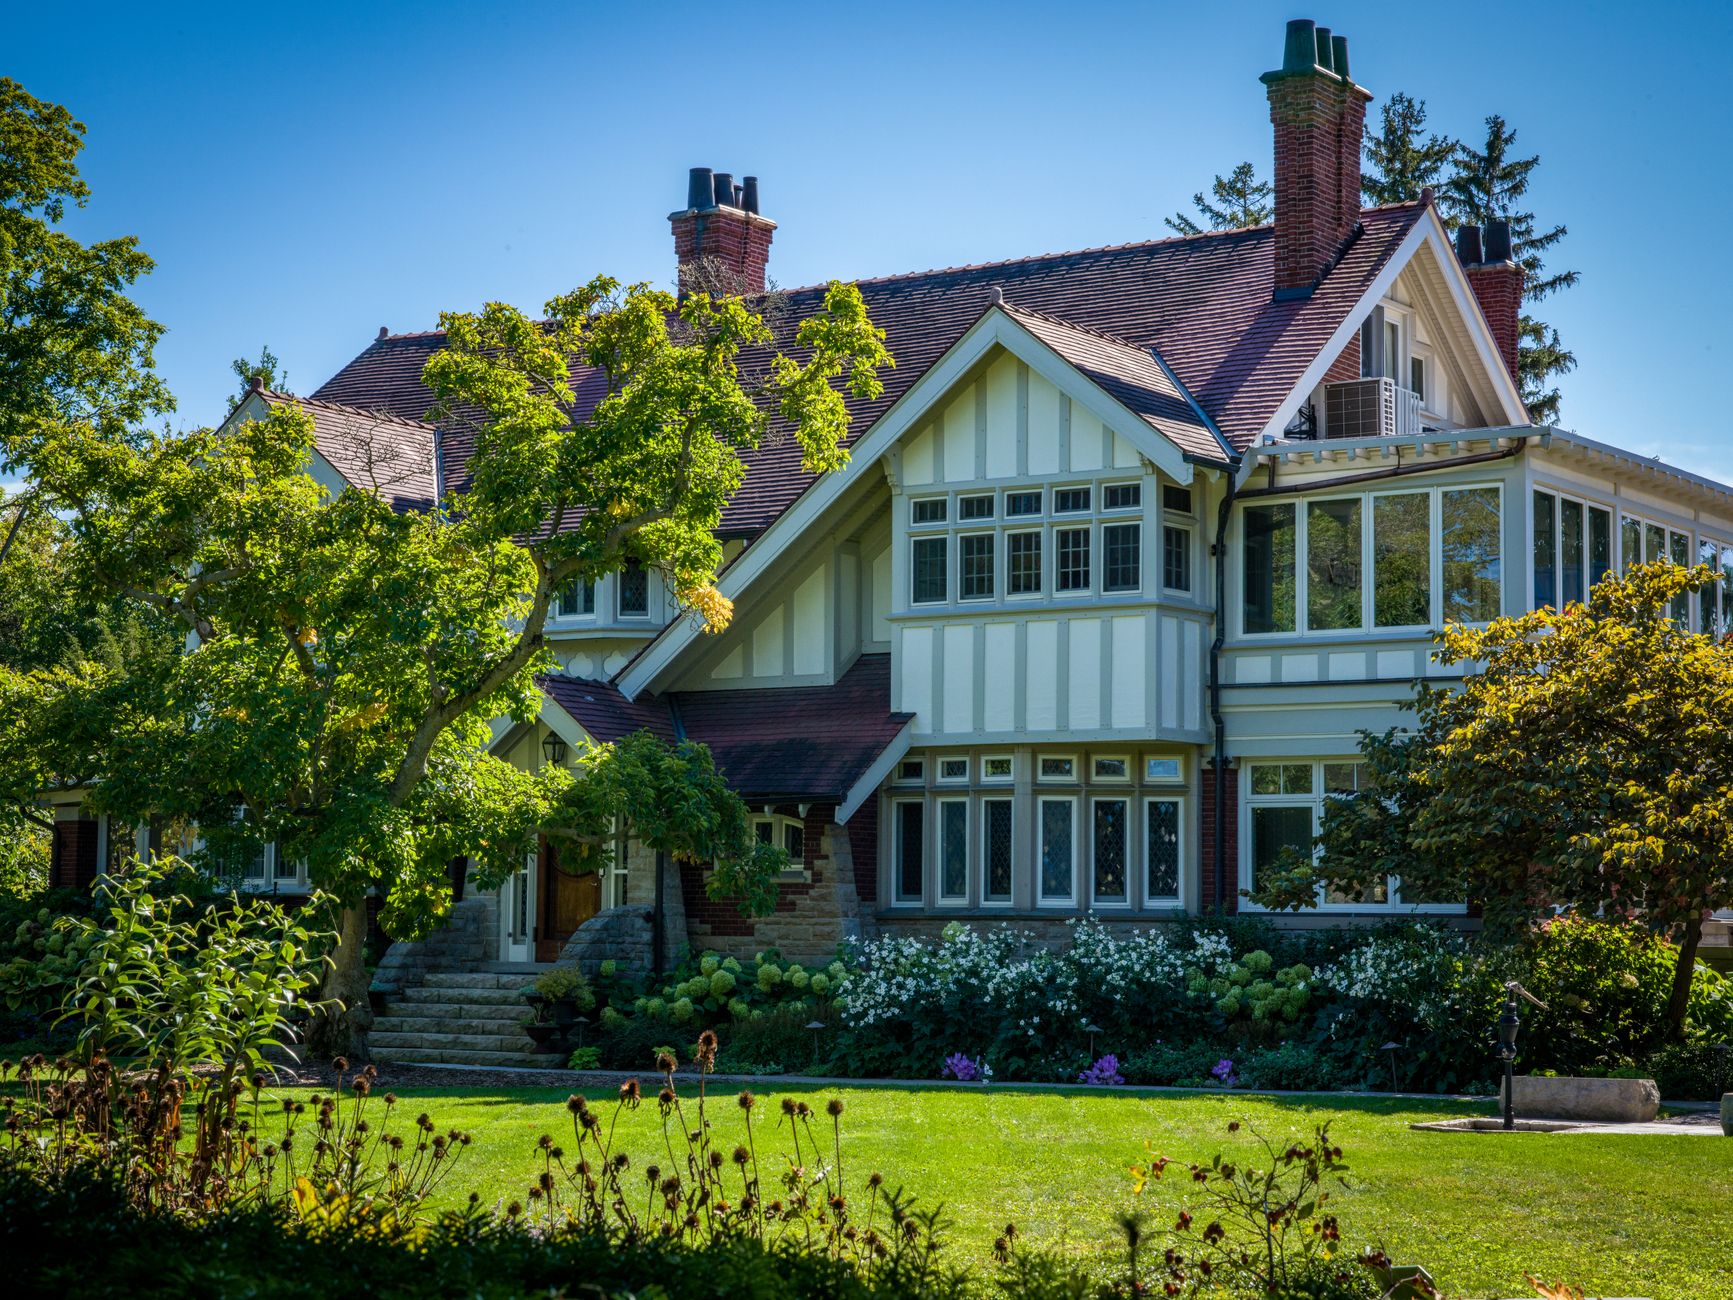
On a warm October morning along North Marengo Avenue in Pasadena, ZIP 91104, a young couple handed over $1.42 million for a restored 1912 Craftsman home. Three weeks after escrow closed, a certified letter arrived from an attorney representing a long-estranged family heir, alleging a forged signature on a deed recorded back in 1998. The buyers did not panic, nor did they lose their life savings. They simply forwarded the letter to their title company. Because they possessed the comprehensive title insurance California buyers rely on to shield their ownership rights, the title insurer hired legal counsel, settled the claim out of court, and absorbed the entire legal bill. Understanding how title insurance California policies function is the single best protection you have against ghosts lurking in your home's public legal history.
What Title Insurance Actually Protects When You Buy
When you buy real estate, you are not just purchasing wood, plaster, and dirt. You are purchasing legal ownership, known in real estate as title. Before a property changes hands, a specialized title examiner digs through decades of public records, deeds, tax rolls, court filings, and divorce decrees to ensure the seller actually owns the house free and clear. Yet even the most thorough public search can miss hidden problems. A fraudulent deed from twenty years ago, an unpaid contractor mechanics lien, an unrecorded property boundary easement, or an overlooked spousal signature can silently cloud ownership rights.
Regular insurance, such as homeowners insurance or auto insurance, protects you against future mishaps like fires, storms, or car accidents. Title insurance operates completely in reverse. It protects you against past mistakes that occurred before you bought the property but resurface after you hold the key. Another distinct feature of title insurance is the payment structure. Unlike regular home insurance with monthly or annual premiums, title insurance requires a single one-time fee paid at the close of escrow. That one fee protects you or your heirs for as long as you own the property in neighborhoods from North Park in San Diego, ZIP 92104, to the quiet coastal enclaves of Santa Barbara.
The Northern and Southern California Divide in Escrow
Navigating title insurance California options requires understanding two distinct policies: the lender policy and the owner policy. Mortgage lenders almost always require buyers to purchase a lender policy. This policy guarantees that the lender holds a valid mortgage lien on the property, protecting the bank up to the total value of the loan balance. It does not protect your equity, your down payment, or your right to remain in the home if a title dispute erupts. For personal protection, you must buy a separate owner policy, which covers you up to the full purchase price of the property.
In the Golden State, regional customs dictate who pays for these policies during escrow. If you buy a modern condo in San Jose, ZIP 95112, or a Victorian in the East Bay hills of Oakland, ZIP 94611, Northern California custom usually dictates that the buyer pays for both the title search and the owner policy. Conversely, if you purchase a mid-century modern home in Palm Springs, ZIP 92262, or a coastal home in Orange County, Southern California tradition usually expects the seller to pay for the buyer's owner title policy while the buyer pays for the lender policy. However, these are local customs, not mandatory state laws. Everything remains entirely negotiable inside your purchase agreement.
Title insurance guards your property rights against past historical mistakes, ensuring that a secret debt from 1998 never becomes your financial burden today.
Three Devastating Mistakes Buyers Make At Escrow
The first critical blunder buyers make is assuming that the mandatory lender policy shields their financial interest. If a rogue contractor files a valid $80,000 mechanic lien against the previous owner and succeeds in court, the lender policy ensures the bank gets paid first if the house is sold. It will not spend a dollar defending your personal equity. Without an owner policy, you must pay that $80,000 out of your own bank account or face a sheriff sale of your property. Skipping an owner policy to save a few hundred dollars at closing creates catastrophic risk.
The second common mistake involves ignoring the preliminary title report delivered during your contingency period. When buying title insurance California real estate transactions demand that buyers review this preliminary report carefully. The report lists all existing covenants, conditions, restrictions, tax assessments, and recorded easements. If the report shows a city utility easement running directly under the backyard where you intend to build a pool, no title policy will cover your financial loss when the city blocks your build permit. The preliminary report reveals existing conditions that the title policy explicitly excludes from coverage.
The third mistake is choosing standard CLTA protection when your property demands an expanded ALTA policy. A standard California Land Title Association policy protects against recorded risks found in public registries. An American Land Title Association Homeowner Policy costs slightly more but covers unrecorded risks, including unpermitted building work done by past owners, boundary fence encroachments, and post-policy forged deeds. In dense urban neighborhoods in downtown Sacramento, ZIP 95816, or sprawling suburban lots in Los Angeles, unrecorded boundary disputes happen frequently, making extended ALTA coverage essential.
How to Read Your Preliminary Report and Secure Coverage
Securing complete ownership protection requires a proactive mindset during escrow. As soon as you open escrow, insist on receiving the preliminary title report within the first five days. Turn directly to Schedule B of the document. Schedule B outlines every exception to your policy—the exact items the title company refuses to insure. Read each line item carefully with your real estate agent or a real estate attorney. Look for recorded liens, private road maintenance agreements, or shared driveway easements that could affect your quiet enjoyment of the property.
If you spot an unexpected lien, demand that the seller clear it before escrow closes. Title insurance is designed to give you clean title, not an insurance claim waiting to happen. Request the ALTA Homeowner Policy upgrade upfront so the title company adds extra protections for unpermitted construction and zoning violations. Paying a small additional fee at closing converts uncertain property history into ironclad peace of mind.
When you close on a home, you buy more than physical square footage; you buy peace of mind. Real estate represents the largest asset most California families will ever hold. By securing an extended owner title policy during escrow, you ensure that no long-lost relative, forgotten creditor, or filing error from thirty years ago can shake the foundation of the sanctuary you built.
Frequently Asked Questions
Is title insurance legally required in California?
State law does not legally mandate owner title insurance for homebuyers in California. However, if you secure a mortgage loan to purchase the home, your institutional lender will universally require a lender title insurance policy to protect their financial investment. Skipping the optional owner policy leaves your personal down payment and equity completely unprotected against historic legal defects.
How much does title insurance cost in California and who pays for it?
Title insurance costs in California typically range between 0.2 percent and 0.5 percent of the total purchase price, payable once at closing. On a $1,000,000 purchase, the title premium generally ranges from $2,000 to $4,000. Payment responsibility varies by local custom: sellers usually pay for the buyer's owner policy in Southern California, while buyers usually pay for it in Northern California.
What is the primary difference between a CLTA policy and an ALTA policy?
A standard CLTA policy covers defects that appear in public recorded documents, such as recorded tax liens, unknown heirs, or court judgments. An extended ALTA policy goes much further by protecting against off-record risks, such as boundary line disputes, unrecorded mechanic liens, physical property encroachments, and unpermitted work executed by prior homeowners.
Ecomstation.ai